
Welcome to Atlas Wealth Advisors inaugural monthly newsletter – The Atlas Update.
The publication’s goal is built around two principles:
- Keep you informed on relevant market/economic topics or,
- Educate you on investment planning techniques and personal financial topics
That said, a current trending topic is the state of the bond market and interest rates. Might it be the so-called “dog that wags the tail”?
When financial professionals discuss bonds, the talk begins and ends with U.S. Treasury market. Notably, the 10-year and 30-year bond.
As prices fall on these bonds, yields rise (this is generally true on all forms of fixed income.)
When yields rise the reaction is a quick repricing of consumer loans, mortgages, auto & credit cards. Importantly, business loan rates move higher which may affect economic conditions in the future.
Beyond this repricing mechanism, the bond market “tentacles” are far reaching as you’ll read. The article below comes to us from Mitch Zacks, CEO and Senior Portfolio Manager at Zacks Investment Management.
The commentary below helps us unpack the market’s reaction to policy issued by the Treasury Department, which ultimately helps us to keep the increased volatility in interest rates in perspective.
The Bond Market Is Sending a Message
Bond yields have moved higher in recent weeks, which has prompted a debate among market participants as to the potential cause: rising inflation expectations, market consternation at rising deficits in the U.S. and abroad, sinking global demand for Treasurys, or some combination of forces.1
10- and 30-Year U.S. Treasury Bond Yields, Year-to-Date
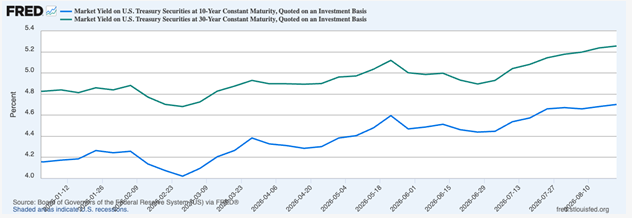
Source: Federal Reserve Bank of St. Louis2
Then, a surprise announcement last week by Treasury Secretary Scott Bessent sent the debate into overdrive.
Secretary Bessent announced plans to expand long-dated U.S. Treasury bond buybacks, with the U.S. Department of the Treasury at least doubling the size of certain buyback operations from $2 billion to $4 billion. The buybacks would focus on the long end of the curve—meaning 10- and 30-year U.S. Treasurys—with the move framed as an effort to support market functioning and liquidity.
The bond market can offer valuable clues about what may lie ahead for investors. Today, shifting yields and changing expectations are sending signals worth watching closely.
But there seemed to be one glaring problem—there was no noticeable issue with liquidity or the ‘plumbing’ of Treasury markets. Treasury auctions were still clearing, dealers were not visibly pulling back, and the market was not facing the kind of forced selling we saw in March 2020. Markets took the news skeptically, and yields ultimately ticked higher—not lower.
I won’t go too deep into the weeds here, but the signal taken from markets was that the Department of the Treasury was intervening in bond markets not because of liquidity issues, but because of pricing issues. In other words, the actual goal was to put a support under bond prices, which equates to an effort to push yields lower, arguably in support of keeping borrowing rates low and financial conditions accommodative.
This was the story that was playing out in headlines last week, but I think it all lacked important context. A $4 billion buyback operation sounds large in isolation, especially after headlines emphasized that Treasury was “doubling” the size of certain operations. But scale is important here, as Treasury cash securities trade around $1 trillion per day in a roughly $32.2 trillion Treasury market. In that context, a $2 billion buyback increase is unlikely to materially change the market’s supply-demand balance on its own.
Rising long-term rates are usually framed as a negative, because they can raise borrowing costs, push mortgage rates higher, and weigh on stock valuations. All these outcomes are real and possible, but rising yields can also serve as an important market signal. When investors demand more compensation to lend for 10, 20, or 30 years, they may be sending a message about inflation, Treasury supply, fiscal policy, or uncertainty. In this sense, markets can ‘demand’ a certain discipline to push policymakers into difficult choices.
There is also a constructive side of the yield story that often gets overlooked.
First, higher yields mean investors are being paid more to own bonds over time. This yield compensation can come with price volatility, but it does improve the overall income profile of high-quality fixed income for long-term investors.
Second, a steeper yield, where long duration bonds see more upward pressure than the short end of the curve, can improve the economics of bank lending. Banks generally fund themselves at shorter-term rates and lend at longer-term rates. When long-term rates rise relative to short-term rates, lending can become more profitable. In the current context, loans and leases in bank credit for all commercial banks were up 7.3% year-over-year as of mid-August, arguably aided in part by rising long duration yields.
Ultimately, higher yields are not automatically positive or negative, but they do carry important information. If yields are rising because growth remains resilient, the economy and corporate earnings may be able to absorb some of the pressure. If yields are rising because inflation expectations or fiscal concerns are worsening, investors should take that signal seriously. For now, I don’t think the recent moves have been sharp enough to suggest a bond market in crisis. But they have been meaningful enough to remind investors that long-term rates, federal borrowing needs, and inflation expectations all deserve close attention.
Bottom Line for Investors
Rising long-term yields deserve attention, but they do not automatically point to a bond market crisis. They are a signal—about inflation, growth, Treasury supply, deficits, and the return investors require to lend money for longer periods.
The right response is not to react emotionally to every move in rates. It is to listen to what the bond market is saying, while keeping the message in perspective.
Of course, the bond market is only one of many forces shaping the investment landscape today.
1 Wall Street Journal. August 21, 2026. https://www.wsj.com/finance/investing/the-wild-week-when-scott-bessent-was-schooled-by-the-bond-market-a244aca2?mod=Searchresults&pos=5&page=1
2 Fred Economic Data. August 26, 2026. https://fred.stlouisfed.org/series/DGS10
This material represents an assessment of the market environment at a specific point in time and is not intended to be a forecast of future events, or a guarantee of future results. This information should not be relied upon by the reader as research or investment advice regarding any funds or stocks in particular, nor should it be construed as a recommendation to purchase or sell a security. Security and advisory services offered through Pinnacle Investments, LLC member FINRA/SIPC. We do not provide tax advice and recommend you seek the advice of a qualified tax professional.
Whether you have questions about year-end planning, new opportunities, or simply want to check in, we’re here as a resource.


