
What we learned last week:
“Politicians and diapers must be changed often, and for the same reason” – Mark Twain
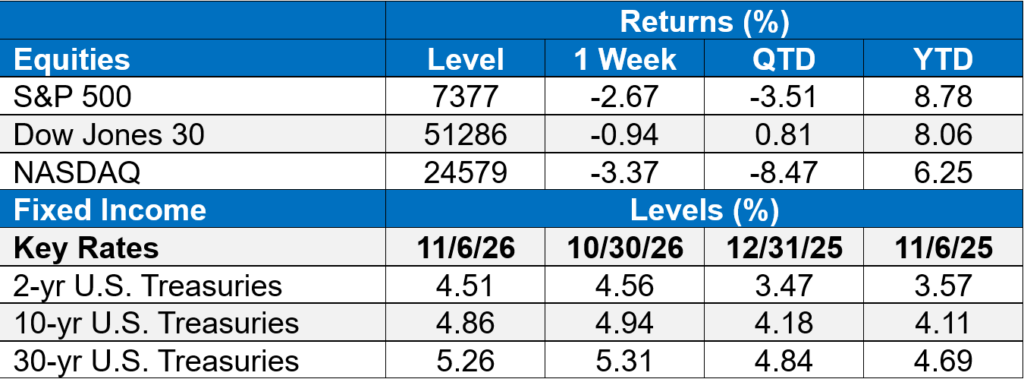
Wall Street’s initial reaction of optimism to the Democratic victories in both the House and Senate vigorously turned on Thursday to the worst one-day loss for all three major stock market averages since April 2025.
Last week major indexes responded to corporate earnings, a sea change in politics and the future economic agenda, and reports on the health of the labor market.
To help illustrate the volatility let’s look at shares of Apple.
Prior to election results Apple’s stock fell during Tuesday’s trading after reporting earnings Monday. Post midterms Apple helped fuel a surge in market indexes with the Dow gaining 1,569 points Wednesday, its best post-midterm day since 1982.
Tuesday night’s midterm elections delivered a decisive Democratic victory. Democrats will take control of Congress and with it an agenda that will shape the economy a change investor initially welcomed Wednesday.
The difference a day can make.
Thursday stock indexes erased all of Wednesday’s gains and the tech-heavy Nasdaq led the fall lower with a decline of more than 5%. Technology hardware companies led in losses. The Philadelphia semiconductor index sold-off by 12%, its worst day since March 2020 as the Democratic sweep of congress and governorships raises data center skepticism.
One specific area of the economy and markets investors expect to change is the AI data center build-out. Texas is a leader in building data centers and in a sharp rebuke voters elected a Democratic U.S. Senator and governor. The governor elect ran on promises to stop data center construction. More than 25% of planned US capacity by 2030 is planned to be built in Texas.
Turning our attention to the health of the US labor market, last week’s ADP National Employment Report showed an employe increase of 86,000 jobs in October, beating Dow Jones estimate for 75,000. Leading the way were jobs in the trade, transportation, and utilities industry.
The Friday jobs report from the Bureau of Labor Statistics echoed ADP’s results and underscored a healthy labor market.
October’s nonfarm payroll employment rose by 165,000 and the unemployment rate ticked down to 4.1%. Additionally, August and September’s employment figures were revised up. The down beat comes from looking under the hood of this report and specifically at wage growth, which is growing at more than 3% year over year. The growth is still slower than the rate of inflation, reducing buying power for consumers.
A major driver of inflation is the cost of energy, and the election also triggered a fall in the price of oil on renewed hopes of an end to the war in Iran.
The week ahead will have a focus on inflation with the Consumer Price Index report due Tuesday. AI will remain in the spotlight as AI company Anthropic is expected to begin its IP road show, helping shape its market value pre-IPO. Of course, as earnings seasons begins to wrap up there are several tech companies reporting that will add to the current AI narrative.
What’s ahead this week:
Economic Events
- Consumer Price Index (CPI) report Tuesday and Producer Price Index (PPI) report Friday may give investors who are expecting a December rate hike additional data to support their view.
- Several speeches by Fed officials will be watched for clues about the future of the Fed policy interest rate
Earnings
- Many of S&P 500 companies have reported earnings this round, on the watch list are three companies with growth attributed to the AI economy:
- Provider of electrical utility services Constellation Energy
- Cloud management and networking Cisco Systems
- Applied Materials who provides manufacturing equipment, services, and software for semiconductor companies around the world
My goal is for you to feel educated and informed about variables we do and don’t have control over and find ourselves working within. I hope to do it in an informative and relatable way. As always, I value your relationship and planning objectives – my door is always open for conversation.


